


What Is Financial Forecasting? And How to Build One You'll Actually Use


Jump to

Quick answer: Financial forecasting is the process of making educated, assumption-based guesses about your business’s future sales, expenses, and cash flow, so you can make proactive decisions instead of reacting to problems after they happen. According to LivePlan’s own survey of small business owners, 90% believe forecasting is crucial to running a healthy business — but only 60% actually have one, usually because it feels too complex or too easy to get wrong. Most forecasts that do exist get built once, handed to a banker, and then ignored, because the founder doesn’t understand or believe the assumptions behind their own numbers. A forecast you’ll actually use is built bottom-up from real business drivers (customers, pricing, cost to sell), doesn’t need to be perfect, is reviewed against actual results every month, and gets revised when the variance is too large to ignore. LivePlan’s Help Me Forecast is built to guide you through that process without a finance background.
What is financial forecasting?
When you create a financial forecast for your business, you’re making educated guesses about what’s going to happen financially. According to Entrepreneur, roughly 30% of businesses close within their second year — often because owners run out of cash, not because the underlying idea failed. Better forecasting and planning can keep a business open long enough to find funding or turn things around.
For an existing business, a financial forecast works like a weather forecast: you’re predicting what’s ahead based on data from the past and present. You’re projecting your future sales, expenses, profits, cash flows, and other financial metrics, based on what you know about your business and your goals.
If you’re a brand-new business with no historical data, you can — and should — still forecast. Forecasting without historical data means making educated assumptions based on your knowledge of the business, then revising as real data comes in. Unlike weather forecasting, building a financial forecast doesn’t require advanced training. If you’re already running a business, you already have your profit and loss statement, balance sheet, and cash flow statement to build from. And you already know your goals — whether that’s reaching break-even, hitting a revenue target, or generating enough income to expand.
Why do most financial forecasts get ignored?
A lot of financial forecasts get ignored because the people who build them don’t take them seriously in the first place. They build a forecast because a banker, investor, or funder asks for it — not because they believe in it. They don’t understand the assumptions. They can’t explain how they arrived at the numbers. It’s a box to check, not a tool to use.
And that shows. If a lender or investor looks at a forecast and it doesn’t look believable — or the founder can’t explain the reasoning behind it — that forecast gets set aside.
The fix is to take the forecast seriously as a bottom-up model, not a top-down guess. Instead of starting with a revenue number you’d like to hit, start with the drivers underneath it:
- Who are my customers?
- How many do I need?
- How many are actually going to buy from me?
- What am I selling, and at what price?
- How much does it cost me to make or deliver each sale?
Work through that process and you end up with a forecast you actually understand — one you can explain, and one you believe in. If you can explain it and believe it, funders will too. That’s what makes a forecast usable rather than decorative.
What makes a financial forecast good, if it’s never going to be perfect?
As Sabrina Parsons, CEO of Palo Alto Software, puts it: “Accurate is different from right. A good forecast needs to represent your business, not predict the future.” You will be wrong. That’s not a flaw in the process — it’s the point. The gap between your forecast and your actuals (the “variance”) is exactly what tells you where to look next.
A good forecast has a few consistent qualities:
Quality | What it means |
|---|---|
Not perfect | You’re expected to miss — the miss is where the useful information comes from |
Specific but simple | Detailed enough to reflect your business, simple enough to actually update (bucket similar revenue streams and expenses rather than listing every SKU) |
Realistic | No hockey-stick growth curves with no reason behind them — your business plan and history should back up the numbers |
Up to date | As real sales, expense, and cash data come in, you use it to revise — an untouched forecast drifts further from reality every month |
Connected to your statements, not identical to them | Your forecast and your P&L/balance sheet/cash flow statement are reviewed together, but the forecast doesn’t need to mirror your accounting line for line |
Easy to update | If updating is a chore, you won’t do it monthly — and a forecast you don’t maintain stops being useful |
Built for scenario exploration | A forecast that’s simple and current is one you can duplicate and adjust to test “what if” questions, without redoing the whole model |
How do you build a financial forecast you’ll actually use?
A forecast isn’t a prediction of exactly what will happen — it’s your best-informed guess, and the value comes from what you do with it afterward.
Say you forecast $10,000 in October revenue and only bring in $8,000. That gap isn’t a failure of the forecast — it’s information. Now you can ask:
- Why didn’t I hit $10,000?
- How many customers did I actually get, compared to what I expected?
- What changed — pricing, discounting, a marketing push that didn’t happen?
That’s the process that turns a forecast into a management tool: build it from real business drivers (customers, pricing, cost to sell, fixed costs), compare actual results to plan regularly, and use the gap to understand your business better — not just to feel behind.
The numbers need to flow through the whole model, not just sit in one statement
The most useful forecast isn’t only a sales and expense prediction — it shows what happens to every part of the business when sales move up or down. Your forecast needs to flow from the profit and loss statement, through the cash flow forecast, into the projected balance sheet, so a change in one driver shows its real impact everywhere else. A forecast that’s just a revenue line isn’t a forecast — it’s a guess with extra steps.
How often should you review and update your forecast?
Review activity | Recommended cadence |
|---|---|
Compare actual results to your forecast | Every month |
Full forecast update/revision | Every quarter (or sooner if variance is high) |
No action needed | Variance is roughly 1–5% — you’re on track |
Time to dig in and revise | Variance hits double digits — find out where, and why |
Reviewing monthly and updating quarterly is a reasonable default, but let your own accuracy set the pace. If you’re consistently within 1–5% of plan, you’re doing a good job and don’t need to touch the model. If variances run into the double digits, that’s your signal to find where the assumption broke and update it.
What are the types of financial forecasts?
Different types of forecasts help you look at different aspects of your business’s financial future.
Sales forecasts
A sales forecast predicts how much you’ll sell in coming months or years. Established businesses look at past sales, current market conditions, and seasonal patterns. Startups build educated guesses from market research and goals.
Expense forecasts
The flip side of a sales forecast — predicting how much you’ll need to spend to keep the business running, from predictable costs (rent, payroll) to the ones that sneak up on you (equipment repairs, rising supplier costs). See our guide to building an expense budget.
Cash flow forecasts
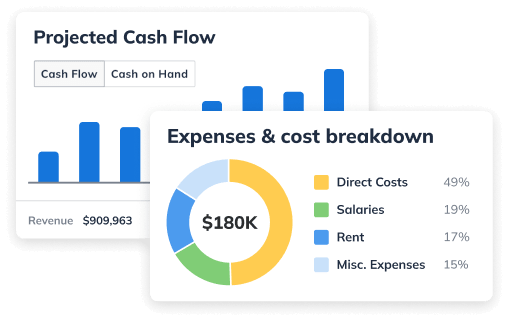
A cash flow forecast tracks money coming in and going out, projected forward — essentially your checking account balance, but for the future. This is what catches a cash crunch before it happens.
Income forecasts
Income (or profit) forecasts zoom in on the bottom line: how much profit will the business actually make after all expenses are paid. Especially useful when you’re pursuing funding.
Scenario forecasts
The business version of “what if.” What if sales drop 20%? What if a new marketing campaign outperforms expectations? Scenario forecasting prepares you for multiple possible outcomes, good and bad.
A second bottom-up example: forecasting a SaaS business
The customer/pricing/cost-to-sell approach isn’t just for product businesses — it works the same way for recurring-revenue businesses, just with different drivers. As Sabrina Parsons describes building her own SaaS company’s forecast, instead of starting with a market-size guess, she builds revenue from metrics she can actually monitor:
- Previous 12 months of sales — a realistic baseline that captures seasonal trends
- Conversion rate — how effectively leads or trials become paying customers
- Monthly churn — the rate customers cancel, which shapes retention strategy and recurring revenue
- ARPA (average revenue per account) — the average value per customer, useful for modeling pricing changes
The principle is the same as the pet-spa or bakery examples: find the numbers you can actually track and control, and build the forecast from those — not from a top-down guess at total market size.
Using scenarios to make tradeoffs, not just to hit a number
A connected forecast is also a tool for comparing two real decisions side by side. Say you’re weighing $10,000 a month in additional marketing spend against hiring another engineer. You can build both as separate “what if” scenarios off your main forecast:
- Scenario A: Add the $10k marketing spend to your expense forecast, and model the resulting increase in leads, conversions, and revenue over the next 6–12 months based on expected ROI.
- Scenario B: Add the full cost of the new hire (salary, benefits, tools), and model the assumed impact — faster development, reduced churn, or an earlier feature launch that drives revenue or retention.
In both cases, you note the assumptions behind the projection — historical ROI on past campaigns, or revenue per engineer on the team. The detail turns a vague conversation about where to spend money into a clear comparison of tradeoffs, using scenario planning.
How does forecasting help you plan for growth?
The most common mistake business owners make when trying to grow isn’t a bad idea — it’s not understanding the cash flow implications of growth. Growth is cash-intensive, even for service businesses: you typically have to hire and train people before they start producing revenue, and inventory ties up cash the moment you buy it, well before you sell it.
Here’s a concrete version of that problem: imagine landing a 50,000-unit order from a major retail buyer. You have to produce and ship the order — on your dime — and if payment terms are 90 days, that invoice sits in accounts receivable for three months before you can use that money to pay your own bills. That’s a large cash outlay that can put an otherwise-successful business under if it isn’t planned for.
That’s why a cash flow forecast matters from day one, not just once a business is established. Before taking on a growth opportunity — a second location, a big order, a new hire — running the forecast tells you whether you can actually afford it: whether you have access to enough capital, or whether you need to slow down, save for a few months first, or line up financing before you commit.
Financial forecasting examples
Emma’s pet spa (expense + sales forecast): Emma is planning to open a luxury pet spa. Her expense forecast shows $28,000 in one-time startup costs and about $12,000 a month to operate. Her sales forecast — built from pricing, expected capacity ramping from 40% to 80%, and a service mix (60% basic grooming, 20% luxury, 10% nail trims, 10% baths) — projects revenue overtaking expenses around month 5 or 6, once she reaches roughly 70–75% capacity.
Whitney’s bakery expansion (expense, cash flow, and scenario forecast): Whitney owns a successful suburban bakery and is considering a second, downtown location. Her expense forecast shows $88,000 in startup costs and $30,600 a month to operate. Her cash flow forecast shows she’ll need about $132,000 to cover the gap until the new location turns profitable — tight against her $150,000 in combined savings and loan funding. Because the margin for error is thin, she builds a scenario forecast — best case, middle ground, and worst case — and finds that even her middle scenario works, but only if she has enough cash runway to survive four to five months of losses.
How do you start financial forecasting in your business?
Financial forecasting isn’t about predicting the future with certainty — it’s about preparing for it, and building a tool you’ll actually come back to. Start with how to create a sales forecast, then download the free cash flow forecast template to begin mapping out your numbers.
Or use financial forecasting software like LivePlan, where Help Me Forecast walks you through the same bottom-up driver questions — customers, pricing, cost to sell, fixed costs — without starting from a blank spreadsheet. LivePlan is trained to ask the right questions and pull relevant research for your specific business, and it builds a connected model so a change to one number flows correctly through your P&L, cash flow, and balance sheet. You can also compare your forecast to actual accounting data and get an AI-powered monthly performance review.
The goal was never a perfect prediction — that’s not possible. It’s proactive planning: a forecast you understand well enough to explain, revise, and actually use to run the business.
Frequently asked questions
Financial forecasting is the process of making educated, assumption-based projections about a business’s future sales, expenses, cash flow, and profitability, used to guide planning and decision-making rather than to predict the future with certainty.
Usually because the forecast doesn’t look believable, or the founder can’t explain the assumptions behind it. A forecast built bottom-up from real business drivers — and one the founder actually understands — is far more likely to be trusted.
Compare actual results to your forecast every month. If your variance is within about 1–5%, no changes are needed. If variance runs into double digits, investigate where it broke and revise — most businesses end up doing a fuller update quarterly.
No. Startups without historical data build forecasts from market research and informed assumptions about customers, pricing, and costs, then revise those assumptions as real data comes in.
A sales forecast predicts revenue alone. A full financial forecast connects that revenue prediction through expenses, profit and loss, cash flow, and the balance sheet, so you can see the complete impact of a change — not just the top-line number.
Yes. LivePlan’s Help Me Forecast guides you through the same driver-based questions a finance expert would ask, then builds a connected financial model behind the conversation — so you don’t need prior finance experience to end up with a forecast that holds together.
A good forecast is realistic, specific but not overly complex, kept up to date with actual results, and easy enough to update that you’ll actually maintain it. It doesn’t need to predict the future correctly — it needs to represent your business well enough to guide decisions.
Mainly because forecasting is perceived as too complex or requiring advanced accounting knowledge. In practice, a forecast built from a handful of business drivers you already track — customers, pricing, costs — doesn’t require a finance background to build or maintain.
A cash flow forecast shows whether you can actually afford a growth move — a new hire, a second location, a large order — before you commit to it, since growth is cash-intensive and the cash often has to go out well before revenue comes in.

Elon Glucklich
Elon is a marketing specialist at Palo Alto Software who works with small business owners, consultants and advisors. He's also a freelance business journalist with over a decade of reporting experience. He has Master of Business Administration from the University of Oregon.
More in Forecasting
forecasting
Can AI Actually Create Accurate Financial Projections for a Pre-Revenue Startup?

forecasting
Budget vs Forecast: Differences Explained + What to Prioritize

forecasting
How to Forecast Expenses and Revenue in LivePlan

forecasting


