

Financial Projections for Startups


Jump to

Quick answer: A startup financial projection has five parts: a revenue forecast, an expense budget, a profit and loss statement, a cash flow statement, and a balance sheet. Building all five by hand in a spreadsheet is where most founders stall. LivePlan's Help Me Forecast is the guided alternative — describe your business and it builds a real, connected financial model behind the chat, no background in finance required.
Imagine for a moment that you're about to embark on a road trip. You've got your destination in mind, your bags are packed, and you're ready to hit the open road. Before setting off, you'd most likely plan out your journey — the distance, the time it'll take, the gas you'd need, even your pit stops. This road map isn't just a smart preparation step; it's your navigation system to reaching your destination successfully.
What is a financial projection for startups?
Think of your startup's financial projections as your business's road map. They are your detailed guide, forecasting the financial performance of your startup over a certain period, often the next three to five years.
Financial projections are not just wild guesses about how much money you'll make. Instead, they're based on reliable data, market research, and sensible assumptions. They show lenders and potential investors that you've done your homework and understand the marketplace.
A lot of founders think a financial projection is just a revenue guess — something like “I think we'll do about $10,000 a month by the end of the year.” That's a start, but it's not a projection. A real projection connects five parts, and without all five, you're guessing at your route, not planning it.
Why are financial projections important?
At the core of every startup, financial projections act like a heartbeat, reflecting the vital signs of your business. Banks, investors and other stakeholders use these projections to gauge your startup's financial health and its potential for growth and profitability.
Financial projection vs. financial forecast: what’s the difference?
The terms are used interchangeably, but there’s a useful distinction:
A projection is typically a forward-looking estimate built for a specific external purpose — a bank loan, an investor pitch, a funding application. It captures a scenario: “if these assumptions hold, here’s where we’ll be in three years.” It’s a point-in-time document.
A forecast is your ongoing internal planning tool, updated regularly as real results come in. It’s less about predicting the future and more about staying calibrated — comparing what you planned against what actually happened, then adjusting. You watch metrics like cash burn rate and cash runway alongside your forecast to catch problems before they arrive.
In practice, the five components are the same for both. The difference is how you use them: a projection you present to a lender; a forecast you review every month alongside your actuals.
LivePlan's Easy Financials handles both. You build the underlying model once, then use it as a living forecast by comparing actuals to plan each month. When you need a projection for a lender or investor, you’re pulling from the same connected model — not rebuilding from scratch.
Financial projection | Financial forecast | |
|---|---|---|
Primary use | External — lenders, investors, funding applications | Internal — ongoing business management and decision-making |
Update frequency | Point-in-time; built for a specific purpose | Updated regularly as actual results come in |
Key question | If these assumptions hold, where will we be? | How do our actuals compare to the plan, and what needs adjusting? |
Components | Same five: revenue, expenses, P&L, cash flow, balance sheet | Same five: revenue, expenses, P&L, cash flow, balance sheet |
Components of financial projections: Your road map's key landmarks
Revenue forecasts: The fuel for your journey
Revenue forecasts are the anticipated income from your startup's products or services — informed predictions based on comprehensive market research, past performance (if available), and your target customer's buying behavior. If you're just starting out, it's possible to create a forecast without any historical data.
Expense budgets: Anticipating the road blocks
Expense budgets estimate the costs your startup will incur — salaries, rent, marketing, and the unexpected flat tire. Estimating these before you invest in them helps you prepare for hurdles and stay financially sustainable.
Profit and loss forecast: Your road trip's mileage log
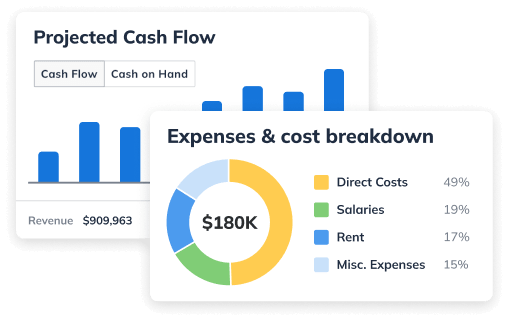
A profit and loss (P&L) forecast tracks the revenue you earn, the direct and indirect costs you incur, and the profit or loss that results. It tells you whether your venture is on the fast lane to profitability or headed for a detour.
Cash flow statements: Monitoring your fuel gauge
A cash flow statement shows how cash moves into and out of your business over a period — your fuel gauge for whether you're running low or have enough to reach the next milestone. Once you have a forecast in place, use it to monitor your cash burn rate and cash runway — two of the most important metrics for knowing how long your cash lasts.
Balance sheets: Checking the condition of your vehicle
The balance sheet is a snapshot of your startup's financial health at a point in time: assets (what you own), liabilities (what you owe), and equity (the ownership stake in the business).
Creating realistic, compelling financial projections
1. Conduct thorough market research
Understand your potential customers: who they are, what they need, what they'll pay. Research your competitors — their pricing, their cost structure — to sharpen your own estimates.
2. Make sensible financial assumptions
Break down assumptions for each component of your financial forecast:
Sales projections start with your potential market size, then your pricing and expected volume.
Expense budgets split into fixed costs (rent, salaries) and variable costs (materials, shipping) — estimate each as precisely as you can.
Profit and loss forecasts start with revenue, subtract cost of goods sold to get gross profit, subtract operating expenses to get operating profit, then account for interest and taxes to land on net profit.
Cash flow forecasts estimate inflows and outflows over a period — your sales projections and expense budget feed directly into this, along with factors like customer payment terms.
Balance sheets snapshot your assets, liabilities, and equity at a given moment.
3. Build your first draft — by hand or in one conversation
Building all five parts by hand, in a spreadsheet, from scratch, is exactly the part that stops most founders before they start. That's where LivePlan's Help Me Forecast comes in: you don't need a finance background. Just describe your business — what you'll sell, how you'll price it, who you'll hire — and it turns that conversation into real numbers, handling the accounting logic for you. LivePlan suggests revenue streams and expenses specific to your industry, then builds the numbers with a simple chat. Behind the chat is a real, connected financial model that stays consistent no matter how many chats you have, so you never have to double-check the math or fall back on a spreadsheet. Prefer to enter the numbers yourself? You can do that too — Help Me Forecast is a guided starting point, not a requirement.
Here's what that looks like in practice. Imagine an entrepreneur launching a pet-sitting and dog-walking business. No historical data yet, just a plan:
- Launching in September
- Expects to sign 15 recurring clients by December, each paying about $150 a month
- Monthly costs: $400 for insurance and bonding, $150 for scheduling software, $300 for marketing, and $800 for a part-time helper starting in November
Rather than opening a blank spreadsheet, she described the business the way she'd explain it to a friend. LivePlan Assistant took that description, asked clarifying questions, and assembled a complete forecast: revenue broken into her recurring client base, an expense budget split into fixed costs, and the profit and loss, cash flow, and balance sheet built out from there — organized the same way a hand-built projection would be, without the hours it usually takes.
From there, she refined it conversationally:
“Add a revenue stream for pet-sitting during holidays, starting in November at $600 for the month.”
“Walk me through my forecast. Where am I most at risk?”
That second question is the one that matters most. It pointed straight to a November cash crunch — the part-time hire and the holiday pet-sitting stream both started the same month, before the recurring client base had fully built up, so cash was tighter that month than any other in the plan. That's exactly what a balance sheet and cash flow statement are supposed to reveal, and exactly what gets missed when a projection stops at a revenue guess.
Once you can see a risk like that, you can plan around it: time a hire to a cash position that actually supports it, build a second revenue stream into the model instead of hoping it helps later, or walk into a tight month already knowing it was coming. And because the underlying model stays connected, your finished forecast includes everything a lender or investor expects to see — a sales forecast, expense budget, profit & loss statement, balance sheet, and cash flow statement — not just the revenue number you started the conversation with.
4. Regularly update your financial projections
Your projections aren't set in stone. Track actual performance against your projections, investigate discrepancies, and adjust — this keeps your projections realistic and surfaces areas of the business that need attention. A financial projection was never supposed to be a single guess you make once and defend forever; it's a living road map, one you keep reading and adjusting as you go.
Presenting your financial projections
Once you've created your financial projections, it's time to share them with potential investors, stakeholders, and your team. Present them clearly, highlight key metrics and trends, and remember: your financial projections tell the story of your startup's potential journey to success. Showing up to a lender or investor conversation with a projection that has all five parts — not just a revenue number — is what makes that story credible.
Frequently asked questions
A revenue forecast, an expense budget, a profit and loss statement, a cash flow statement, and a balance sheet. All five need to connect to each other — a revenue number alone isn't a projection.
Yes. Startups without historical data build projections from market research, informed assumptions, and a clear pricing and cost structure. Learn how to build a forecast with no historical data.
No. You describe your business in plain language — what you'll sell, how you'll price it, who you'll hire — and Help Me Forecast handles the accounting logic behind the scenes. You end up with a connected financial model even if you've never built one before.
Generic AI can generate numbers that look right but can't guarantee they add up or stay consistent between conversations. Help Me Forecast is built on a real, connected financial model — change one assumption and it flows through your entire forecast correctly, every time, without you needing to double-check the math or work in a spreadsheet.
Regularly — compare actual results against your projections as real data comes in, and adjust assumptions when there's a meaningful gap. A projection is a living document, not a one-time exercise.
They expect all five. A revenue number alone doesn't show whether the business can cover its costs, stay solvent month to month, or maintain a healthy balance sheet — which is exactly what lenders and investors are evaluating.

Noah Parsons
Before joining Palo Alto Software, Noah Parsons was an early Internet marketing and product expert in the Silicon Valley. He joined Yahoo! in 1996 as one of its first 101 employees and become Producer of the Yahoo! Employment property as part of the Yahoo! Classifieds team before leaving to serve as Director of Production at Epinions.com. He is a graduate of Princeton University.Noah devotes most of his free time to his three young sons. In the winter you'll find him giving them lessons on the ski slopes, and in summer they're usually involved in a variety of outdoor pursuits.Noah is currently the COO at Palo Alto Software, makers of the online business plan app LivePlan.
More in Forecasting
forecasting
Flexible Cash Flow Assumptions in Your Forecast: New Feature

forecasting
Live Forecast Update — A New LivePlan Forecasting Feature

forecasting
Why Financial Forecasting in a Crisis is Vital for Combating Uncertainty

forecasting