What Is a Balance Sheet, and How Do You Read It?

Jump to

Every business plan should include three key financial statements: a profit and loss statement, a cash flow statement, and a balance sheet.
The balance sheet is the statement that is most often misunderstood, which is problematic because it is the statement that tells you what your business owns and what it owes. If you’re building or running a business, you’ll need to know how to read and understand your balance sheet.
What is a balance sheet?
Your balance sheet is a financial statement that summarizes your company’s assets (what you own), your liabilities (what you owe), and equity (money invested into the business, plus profits).
The balance sheet doesn’t show trends, but instead shows the financial state of a company at a specific point in time.
The balance sheet always follows this formula:
Assets = Liabilities + Equity
Reading and understanding your balance sheet
Balance sheets get their name from the fact that they always have to balance out, based on the formula above.
Assets must always equal liabilities plus equity. This might sound complicated at first, but it’s actually pretty straightforward: A company needs to pay for the things it owns (assets) by either borrowing money (liabilities) or getting money from investors and profits (equity).
Let’s look at an example so you can see how this works. If your business gets a $10,000 loan from the bank, you now have $10,000 in cash in your business bank account. This is your asset.
But, you also now owe the bank $10,000, which is your liability. The two sides of the equation balance out because the money you owe equals the amount of money that you have added to your bank account.
$10,000 cash (asset) = $10,000 loan (liability)
If you also get a $5,000 investment, your assets will increase as you add that cash to your bank account, but equity will also increase because investors now own a piece of the company.
$15,000 cash (asset) = $10,000 loan (liability) + $5,000 investment (equity)
Equity will also include the profits the company keeps over time. Those profits will also show up on the assets side, appearing as cash, investments, inventory, or some other asset.
The three categories here (assets, liabilities, and equity) are each made up of various sub-accounts. Depending on your industry, there can be different accounts in each section. Below, we’ll define some of the most common things you’ll see in each section.
What’s included in assets?
Assets are divided into two primary groups: current assets and long-term assets.
Current assets can be converted into cash in a year or less. They typically include cash, stocks, accounts receivable, prepaid expenses, and inventory.
Keep in mind that the value of the inventory listed on your balance sheet is what you paid for that inventory, not what it might be worth if you sold it to customers. Your asset is your actual cost to purchase the inventory.
Long-term assets (also called fixed assets) are tangible assets that are for long-term use, such as equipment, machinery, vehicles, land and buildings, furniture and fixtures, and leasehold improvements. You can sell long-term assets and turn them into current assets, but generally speaking, long-term assets will provide value to your business for many years.
What’s included in liabilities?
Liabilities are the money that a business owes to other people or businesses. These could be bills, loans, deferred taxes, and so on. Just like assets, liabilities are divided into current and long-term groups.
Current liabilities are business obligations due within one year. These typically include short-term loans (including lines of credit), current maturities of long-term debt, accounts payable, accrued payroll and other expenses, and taxes payable.
Long-term liabilities are business obligations that are due outside of one year, such as any bank debt or shareholder loans with maturities longer than one year.
What’s included in equity?
The equity section of the balance sheet is the sum of all shareholder/owner money invested in the business plus accumulated business profits.
How the balance sheet works with your P&L and cash flow statement
Your balance sheet complements your profit and loss statement and your cash flow statement to give you a complete financial picture of your business.
Your profit and loss (also known as a P&L or an income statement) tells the story of your sales and your expenses.
Your cash flow statement tells you how money is moving into and out of your business.
But, neither of these statements gives you a complete picture of where your business stands financially. That’s where your balance sheet comes into play.
The three statements are linked. When you make a sale on credit, it shows up as revenue on your P&L and as accounts receivable on your balance sheet. When the customer pays, cash moves on your cash flow statement and your balance sheet. That’s why a financial forecast built as a connected three-statement model is so much easier to trust than three separate spreadsheets. Having these three statements linked together allows you to immediately see what the sale does to profits, cash flow, and ultimately cash in the bank. If you have an unexpected expense, you should be able to plug it into your linked financial forecast and once again immediately see what it does to your business across profits, cash flow, accounts payable, and cash in the bank.
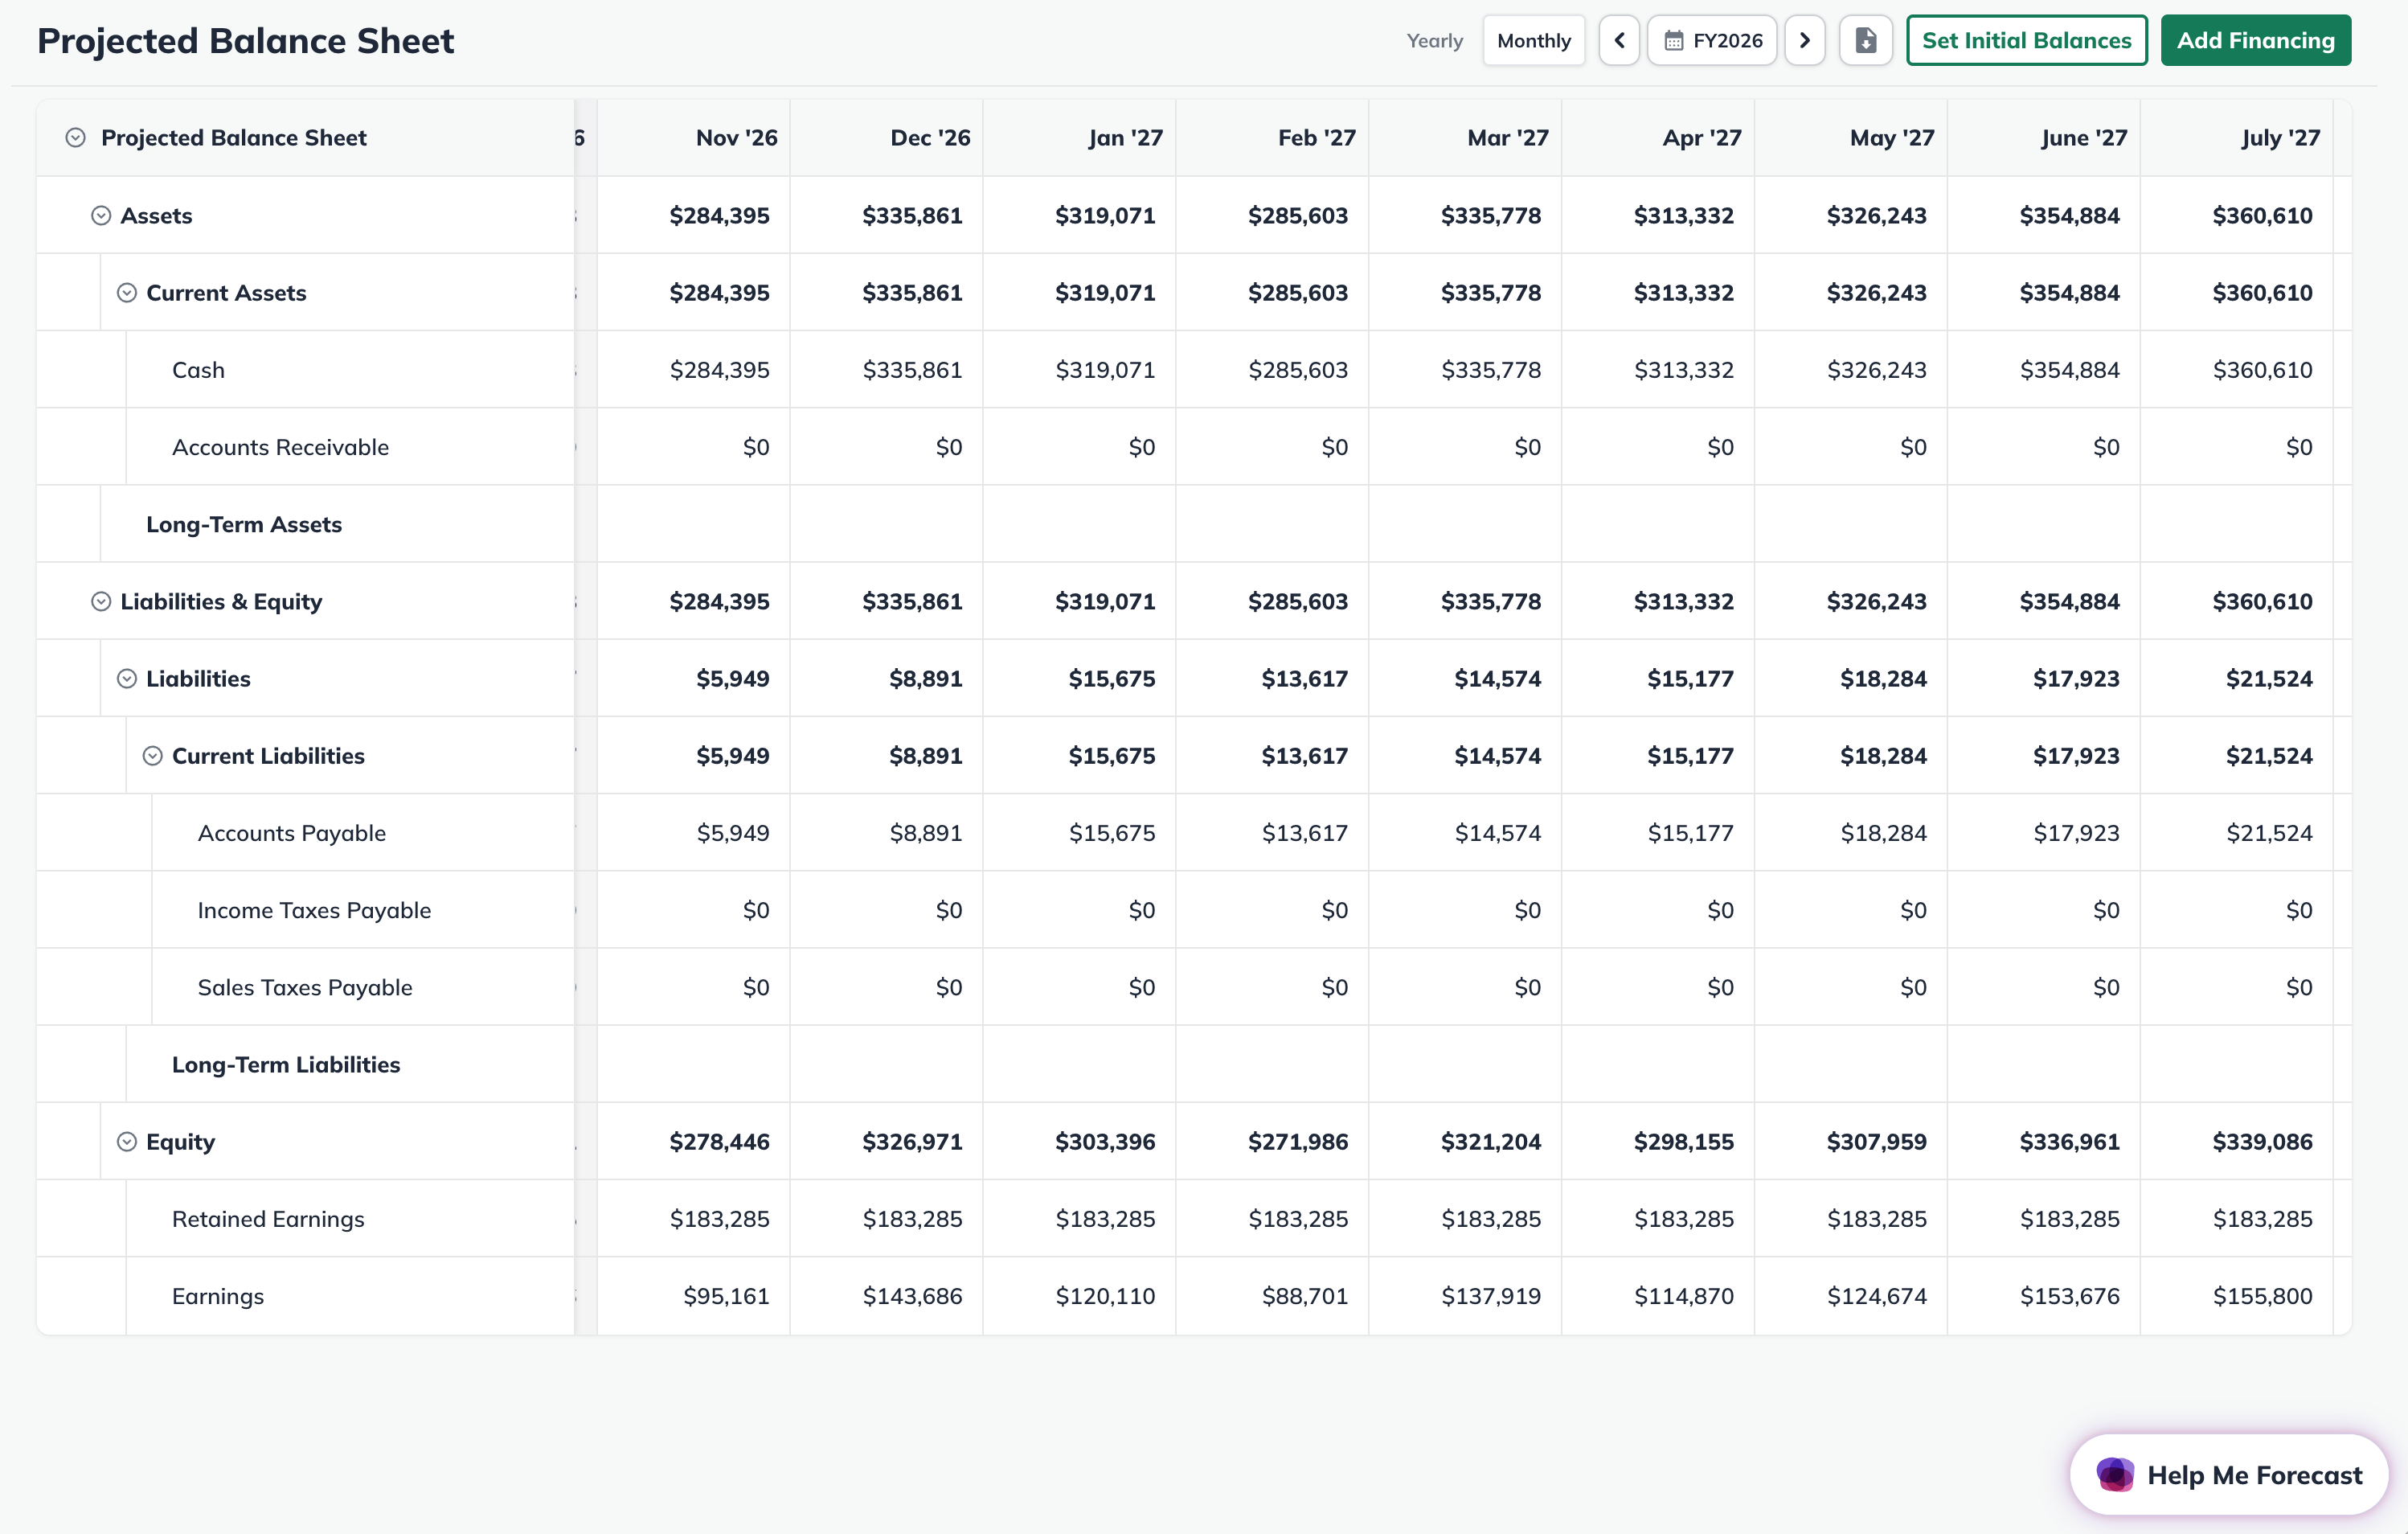
Example of a balance sheet
What does a balance sheet typically look like? Check out this example from LivePlan.
How to use the balance sheet
Find your net worth. Your balance sheet can provide a wealth of useful information to help improve your financial management. For example, you can determine your company’s net worth by subtracting your balance sheet liabilities from your assets.
Spot potential cash issues. Perhaps the most useful aspect of your balance sheet is its ability to alert you to potential cash shortages. You can look at the amount of cash you have in the bank and quickly see how much you owe your vendors (accounts payable). If your accounts payable number is greater than the amount of cash you have on hand, you’ll need to have a plan for either increasing the amount of cash you have or paying your bills more slowly over time. Of course, looking at your cash flow forecast together with your balance sheet gives you the best information to make informed decisions about your cash position.
How to analyze your balance sheet using ratios
A great way to do a balance sheet analysis is to monitor key ratios that will give you a quick snapshot of your business’s financial health. There are two easy-to-figure-out ratios that can be computed from the balance sheet to help determine whether your company will have sufficient cash to meet current financial obligations.
Current ratio
The current ratio measures your business’s ability to pay its short-term liabilities. It shows whether your company has enough current (i.e., liquid) assets on hand to pay bills on time and run operations effectively.
Current Ratio = Current Assets / Current Liabilities
You want this ratio to be above 1. If the ratio falls below 1, it’s a warning sign that your business may not be able to pay its debts when they become due. This isn’t always bad news — it just signals that you should look into how your business is running.
The higher the current ratio, the better, although industry standards can vary widely. The acceptable current ratio for a retail business, for example, is different from that of a manufacturer.
Quick ratio
The quick ratio is similar to the current ratio but excludes inventory, since inventory can take time to turn into cash. It’s a stricter test of whether you can pay your bills with what you have on hand now.
Quick Ratio = (Current Assets − Inventory) / Current Liabilities
Like the current ratio, you want this number to be higher than 1, and the higher the number, the better. Just as with current ratios, desirable quick ratios differ from industry to industry.
You can use industry benchmark tools, such as the ones found in LivePlan, to determine if your balance sheet ratios are in line with your industry averages.
How to do a monthly balance sheet review
As a business owner, you’re carefully watching your sales and hopefully keeping track of your expenses and bank account balance. But beyond the day-to-day monitoring of your key financial numbers, you should take a step back once a month to do a monthly financial review meeting.
A key part of that meeting is taking a look at your balance sheet. Here are the questions your balance sheet can answer for you that your other financial statements can’t address:
How much money is in the bank?
This is probably one of the most frequent and most important questions that a business owner asks themselves. Knowing what you have in the bank is the key to most financial decisions. The amount of cash that your business has on hand is listed as a current asset.
Are you owed money?
You’ll find this number in the accounts receivable row on your balance sheet. If your customers don’t pay you in cash—you send them invoices and they pay later—this is where you’ll find what’s owed to you.
As your sales increase, this number is likely to increase, too. If some customers aren’t paying you as quickly as you would like, you’ll see this number grow. For most businesses, figuring out how they can convert accounts receivable into cash is an ongoing challenge.
How much inventory do you have on hand?
If you sell products, you deal with inventory. While your balance sheet doesn’t tell you exactly what products you have on hand and how many of each, it does tell you the value of that inventory.
What other assets do you have?
If you own the building that your business is in, for example, that would be a long-term asset. In terms of a monthly review, you’re probably less likely to need to keep close track of this number. It’s not likely to change significantly unless you are investing a lot of money into new buildings and large equipment.
What bills are outstanding?
Like most businesses, you probably don’t pay bills the day they come in — you probably wait 15, 30, or maybe even more days before paying. Those accumulating bills will show up on the accounts payable line of your balance sheet.
How much cash you have in the bank and how much your customers owe you will likely be factors as you consider how quickly you want to pay those bills.
How much do you owe?
In addition to bills from your vendors, your business is probably accumulating other debts, like sales tax that you’re collecting from your customers and need to pay to the government, income taxes, and other short-term loans. You may also have long-term liabilities, like a 30-year loan for your building.
Everything that you owe will total up in the liabilities section of your balance sheet, showing you exactly how much your business owes.
Balance sheet reviews should be quick and easy
The reality is that it probably took you longer to read this article than it will take you to review your balance sheet on a monthly basis. With a little practice and an understanding of what the numbers mean, you’ll be able to read a balance sheet in a couple of minutes.
If you connect your accounting software, LivePlan’s Performance Dashboard and Monthly Review can pull your balance sheet and explain what changed month to month. This is a great report to keep tabs on and help make sure your business is fiscally healthy.
Build your balance sheet automatically
When you’re creating a forecast for your business, it’s generally much easier to use a tool like LivePlan to build your forecasted balance sheet for you. LivePlan creates a connected profit and loss, cash flow statement, and then the balance sheet automatically from your forecast, so a change in one flows through to the others.
You can also download our free Balance Sheet Template and build one on your own.
For more business concepts made simple, check out these articles on direct costs, cash burn rate, net profit, operating margin, accounts payable, accounts receivable, cash flow, profit and loss statement, and expense budgeting.
Frequently asked questions
Assets = Liabilities + Equity. Everything a business owns is paid for either by borrowing (liabilities) or by owner investment and retained profits (equity), so the two sides always match.
An income statement, or P&L, shows sales, expenses, and profit over a period of time, like a month or a year. A balance sheet shows what your business owns, what it is owed, and what its total value is at a single point in time.
Monthly is a good rhythm for most small businesses. A quick monthly review shows your cash, what customers owe you, and what you owe, so you can spot cash problems early.
A current ratio above 1 means your current assets cover your current liabilities. Higher is generally safer, but what’s normal varies by industry, so compare your ratio to industry benchmarks.

Noah Parsons
Before joining Palo Alto Software, Noah Parsons was an early Internet marketing and product expert in the Silicon Valley. He joined Yahoo! in 1996 as one of its first 101 employees and become Producer of the Yahoo! Employment property as part of the Yahoo! Classifieds team before leaving to serve as Director of Production at Epinions.com. He is a graduate of Princeton University.Noah devotes most of his free time to his three young sons. In the winter you'll find him giving them lessons on the ski slopes, and in summer they're usually involved in a variety of outdoor pursuits.Noah is currently the COO at Palo Alto Software, makers of the online business plan app LivePlan.
More in Planning
planning
How to Write an Online Fitness Business Plan
planning
How to Write a Real Estate Business Plan + Example Templates
planning
What Entrepreneurs Really Think About Using AI to Write Business Plans
planning